 FaithShield Insurance
What happens in the first 90 days
- The payment is still due. The bank does not pause the loan for grief. The next payment comes due on the same date, along with property taxes and homeowners insurance in the escrow.
- The servicer has to be told. The surviving spouse or family contacts the mortgage company, sends a death certificate and asks to be recognized on the account. Consumer Financial Protection Bureau rules require servicers to communicate with confirmed surviving family members.
- The loan can stay as it is. A federal law (the Garn-St Germain Act) stops a lender from calling the whole loan due just because the home passed to a spouse or child. The CFPB has also made it easier for a surviving spouse to be added to the existing loan.
- The budget changes overnight. The same payment now comes from one paycheck, often while the family is paying for a funeral and missing work.
Why this is the moment families lose homes
A CFPB report found that mortgage companies often create obstacles for surviving family members after a death: lost paperwork, wrong information and delays while payments keep coming due. Grief and the fear of losing the house arrive at the same time. No family should carry both.
Florida homestead rules decide who inherits the home itself, and an estate attorney can walk you through the title. The loan still has to be paid either way.
How Florida families keep the house
Mortgage protection is life insurance designed around your mortgage. When the person who helps pay for the house passes, the policy pays the family directly, and life insurance death benefits are generally received income-tax free. Your family decides how to use it: pay off the loan, keep making payments, or cover the bills while they heal.
| Without coverage | With mortgage protection | |
|---|---|---|
| The monthly payment | Comes from one income | Paid off, or covered by the policy |
| Who receives the money | Nothing to receive | Your family, not the bank |
| Time to grieve | Little: bills keep coming | Room to breathe and heal |
See your real numbers
A few quick questions about your home and your health. You see the coverage and the monthly cost for your family. No pressure, nothing to buy. 🔒 Your information stays with me and is never sold.
Questions families ask
Does the bank forgive the mortgage when my spouse dies?
No. The loan stays in place and payments are still due. The bank expects the balance to be paid by the surviving owner or the estate.
Can my spouse keep the loan without qualifying again?
In most cases, yes. Federal law stops the lender from calling the loan due when the home passes to a spouse or child, and CFPB rules let a surviving spouse be added to the existing loan.
Does PMI pay off the house when someone dies?
No. PMI protects the lender when a loan defaults. It does not pay your family anything.
How much coverage do we need?
Most families start with the mortgage balance plus a cushion for a few months of bills. Our free quote shows the coverage and the monthly cost for your family.
Meet your broker
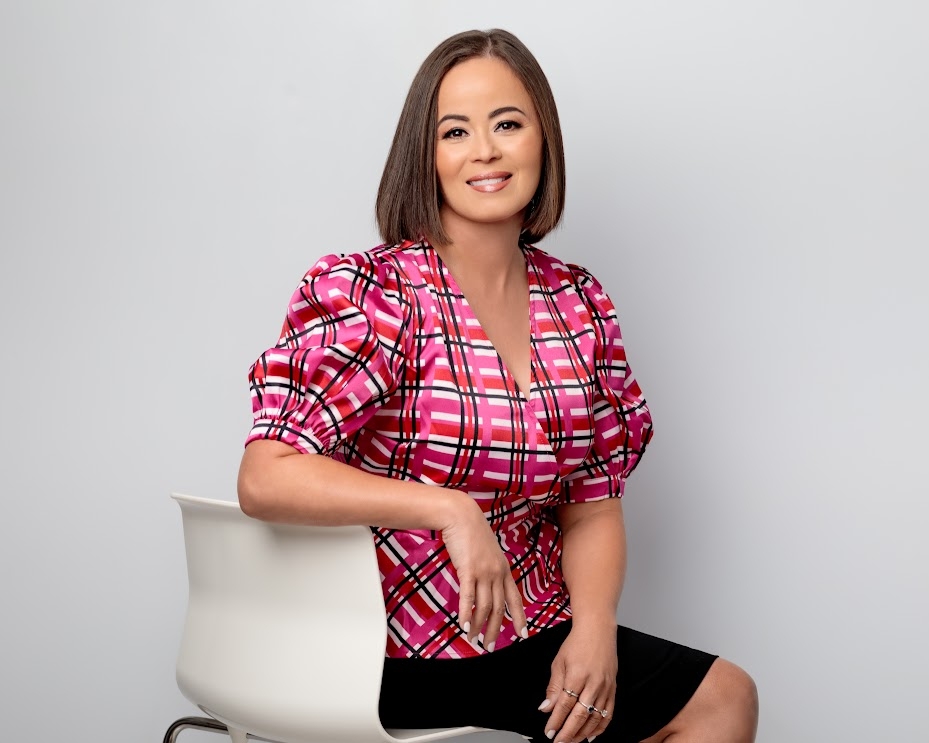
Rhina Jasmyn is a licensed insurance broker in Florida (life, health and variable annuities) and the founder of FaithShield Insurance. After 15+ years in real estate helping families buy their homes, she now helps them keep them. English and Spanish.
Sources
- CFPB: rules to assist surviving family members
- CFPB: mortgage companies create obstacles for homeowners after death or divorce
More answers
This page is general education, not legal or tax advice. Coverage, prices and approval depend on each carrier.